Loan Moratorium Calculator Online– See Your EMI Impact
Find out how a payment moratorium can affect your EMI, total interest, and loan repayment period.
✓ Free to use · No signup · Instant results · Privacy-friendly
See How a Loan Moratorium Can Change Your Repayment
A loan moratorium may pause your EMI payments, but interest can continue to accrue. Estimate the potential impact on your EMI, total interest, outstanding balance, and loan repayment period.
Free Online Loan Moratorium Calculator
Estimate the impact of a loan payment moratorium on your outstanding balance, EMI, additional interest and repayment cost.
Current Loan Details
Enter the details of your existing loan.
Moratorium Details
Enter the proposed payment holiday.
Moratorium Impact
Compare your estimated loan cost before and after the moratorium.
Based on the assumptions entered above.
Without Moratorium
With Moratorium
Interest may continue to accrue while EMI payments are paused. Depending on the lender’s terms, accrued interest may be added to the outstanding balance, paid separately, or recovered through a higher EMI or longer repayment period.
What Is a Loan Moratorium?
A loan moratorium is a temporary period during which a borrower is allowed to pause or defer scheduled loan payments, usually for a specified number of months. It may be offered by a lender during financial difficulties, specific relief programs, or under the terms of certain loan agreements.
A moratorium does not necessarily mean that the loan interest is waived. In many cases, interest continues to accrue on the outstanding loan balance during the moratorium period. The accumulated interest may then increase the amount payable after the moratorium or affect the loan’s repayment schedule.
For example, if you have a home loan with a monthly EMI and receive a six-month moratorium, you may not have to make the regular EMI payments during those six months. However, the interest applicable during the deferred period may still need to be paid later, depending on your lender’s terms.
Key Points to Know
- EMI payments may be temporarily deferred during the approved moratorium period.
- Interest may continue to accrue even when regular payments are paused.
- The outstanding loan balance can increase depending on how accrued interest is handled.
- Your EMI, loan tenure, or total repayment cost may change after the moratorium.
- The actual impact depends on the loan agreement and lender’s calculation method.
Use the Loan Moratorium Calculator above to estimate how a payment break could affect your loan repayment and overall interest cost.
How Does a Moratorium Affect Your Loan?
A loan moratorium can provide temporary relief by allowing you to defer your scheduled EMI payments. However, pausing your EMI does not necessarily pause the interest on your loan. If interest continues to accrue during the moratorium, the total cost of the loan may increase.
The effect depends on how the lender treats the interest accumulated during the moratorium. It may be added to the outstanding principal, collected separately later, or recovered through revised EMIs or an extended loan tenure.
What Can Change After a Moratorium?
1. Outstanding Loan Balance
If accrued interest is added to the loan balance, the amount you owe after the moratorium can be higher than before the payment break.
2. Total Interest Cost
Because interest may continue to accrue while EMIs are deferred, you could pay more interest over the remaining life of the loan.
3. EMI Amount
Depending on the lender’s repayment method, your EMI may increase after the moratorium if the remaining tenure is kept unchanged.
4. Loan Tenure
Alternatively, the lender may keep the EMI broadly unchanged and extend the repayment period to recover the additional amount.
5. Total Repayment
The combination of accrued interest, revised EMI, and any change in tenure can increase the overall amount repaid over the life of the loan.
Why Calculate the Impact?
A moratorium can be useful when you need short-term cash-flow relief, but it is important to understand its long-term repayment cost. Comparing your loan before and after the moratorium can help you make a more informed borrowing decision.
The calculator above provides an indicative estimate based on the loan amount, interest rate, remaining tenure, and moratorium period entered by you. Actual results can vary according to your lender’s terms and calculation method.
How Is Moratorium Interest Calculated?
During a loan moratorium, interest may continue to accrue even though regular EMI payments are temporarily deferred. The interest accumulated during this period depends on the outstanding loan balance, applicable interest rate, and length of the moratorium.
A simplified calculation for estimating interest during a moratorium is:
Moratorium Interest ≈ Outstanding Loan Balance × Periodic Interest Rate × Moratorium Period
For example, suppose the outstanding loan balance is ₹10,00,000, the annual interest rate is 10%, and the moratorium period is 6 months. Using a simple monthly estimate:
- Outstanding balance = ₹10,00,000
- Annual interest rate = 10%
- Monthly interest rate = 10% ÷ 12
- Moratorium period = 6 months
- Estimated interest = ₹10,00,000 × (10% ÷ 12) × 6
- Estimated interest = ₹50,000
This is a simplified illustration. Actual loan interest may be calculated using the lender’s specific daily or monthly interest calculation method, and the treatment of unpaid interest can also vary.
What Happens to the Accrued Interest?
The interest accumulated during the moratorium may be handled in different ways depending on the loan agreement. It could be added to the outstanding balance, recovered through revised EMIs, collected separately, or result in an extension of the loan tenure.
Therefore, the calculator should be treated as an estimate rather than a statement of the amount payable by a particular lender. Always check your loan agreement or lender’s repayment schedule for the actual treatment of moratorium interest.
Loan Moratorium Calculation Example
Consider a borrower with an outstanding loan balance of ₹10,00,000, an annual interest rate of 10%, and a 6-month moratorium.
If interest continues to accrue during the moratorium, a simplified monthly calculation would be:
Monthly Interest = ₹10,00,000 × 10% ÷ 12 = ₹8,333.33
For six months:
Estimated Moratorium Interest = ₹8,333.33 × 6 = ₹50,000
If this accrued interest is added to the loan balance, the outstanding amount could become approximately ₹10,50,000 before considering any subsequent repayments or lender-specific adjustments.
Example at a Glance
| Particular | Example Value |
|---|---|
| Outstanding loan | ₹10,00,000 |
| Annual interest rate | 10% |
| Moratorium period | 6 months |
| Approx. monthly interest | ₹8,333 |
| Approx. interest during moratorium | ₹50,000 |
| Illustrative balance after accrual | ₹10,50,000 |
This example uses a simplified interest calculation for illustration. Actual results can differ because lenders may calculate interest daily or monthly and may apply different rules for capitalization, repayment, EMI revision, or tenure extension.
Use the calculator above with your own loan details to get an indicative estimate of the potential moratorium impact.
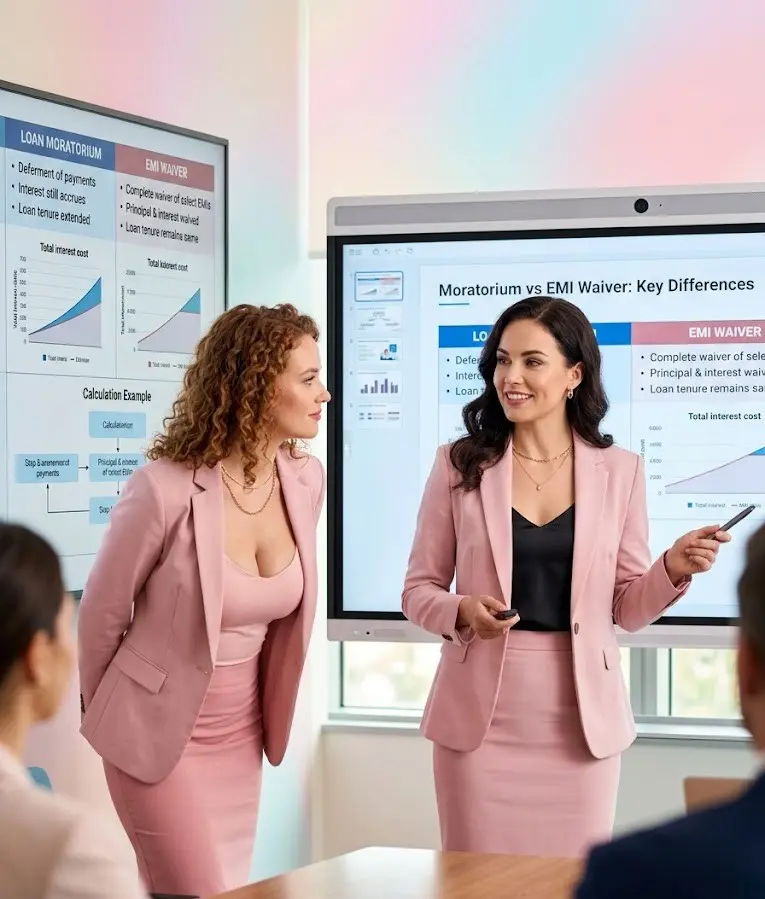
Moratorium vs EMI Waiver
A loan moratorium and an EMI waiver are not necessarily the same thing. A moratorium generally means that scheduled payments are deferred for a temporary period, while an EMI waiver would mean that a particular payment or amount is actually forgiven under the applicable terms.
In a moratorium, interest may continue to accrue even though you are not making your regular EMI payments. With a genuine waiver, the waived amount may not have to be repaid, depending on the lender’s terms and the specific relief arrangement.
| Feature | Loan Moratorium | EMI Waiver |
|---|---|---|
| Regular EMI payment | Temporarily deferred | May be forgiven, if specifically approved |
| Interest during period | May continue to accrue | Depends on the waiver terms |
| Amount deferred | Usually payable later | May not be payable if genuinely waived |
| Loan cost | Can increase | May or may not increase |
| Loan tenure | May be extended | Depends on the arrangement |
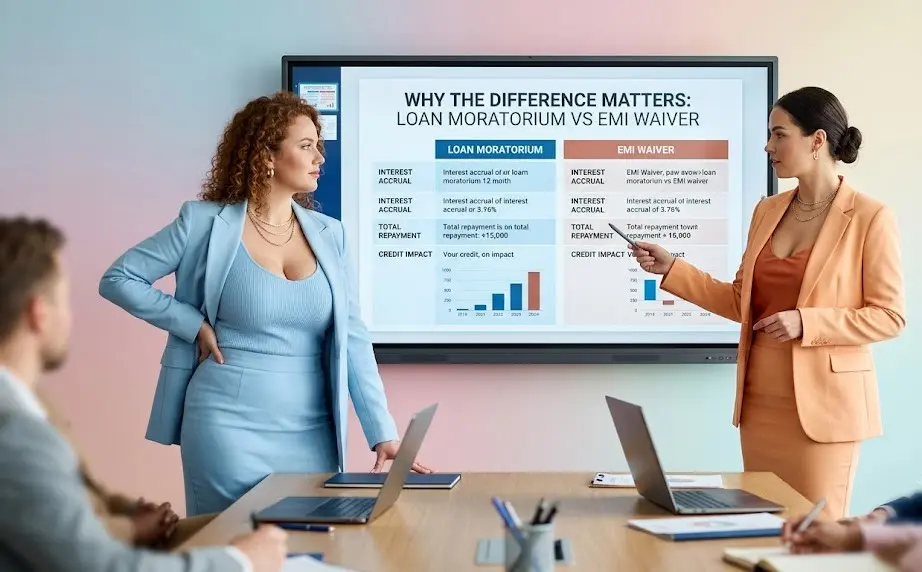
Why the Difference Matters
Choosing or evaluating a moratorium based only on the fact that “EMI payments are paused” can give an incomplete picture. The accumulated interest and the way it is recovered can affect your future EMI, repayment period, and total loan cost.
Before accepting a moratorium, check whether the lender is deferring the EMI, waiving the EMI, deferring only the principal, or continuing to charge interest during the relief period.
The exact treatment depends on the loan agreement and applicable lender terms. Use the calculator above to estimate the potential financial impact based on your own loan details.
When Does a Loan Moratorium Make Sense?
A loan moratorium can provide temporary cash-flow relief when you are unable or find it difficult to continue making regular EMI payments. However, because interest may continue to accrue, a moratorium can increase the overall cost of borrowing.
A moratorium may be worth considering when the short-term financial relief is more important than the potential additional loan cost.
Situations Where a Moratorium May Help
- Temporary cash-flow pressure: You expect your income or cash flow to improve after a short period.
- Unexpected financial commitments: A temporary payment break can help manage a significant short-term expense.
- Business or income disruption: A borrower may need additional time to restore regular cash flows.
- Avoiding missed payments: An approved moratorium may help maintain repayment discipline when offered under suitable terms.
Things to Check Before Choosing a Moratorium
Before accepting a moratorium, understand how interest will be calculated and recovered. Check whether the accumulated interest will be added to the outstanding balance, collected separately, recovered through higher EMIs, or result in an extension of the loan tenure.
Also compare the cost of the moratorium with the benefit of retaining cash during the deferred period. A payment break can provide immediate relief, but the additional interest or extended repayment period may increase your total loan cost.
The right choice depends on your individual cash-flow situation and the specific terms offered by your lender. Use the Loan Moratorium Calculator to estimate the potential impact before making a decision.
Loan Moratorium Calculator FAQs
Explore More Loan & Finance Calculators
Loan planning involves more than just calculating your EMI. Compare monthly payments, total interest, loan affordability, repayment tenure, and potential prepayment savings with our range of free loan and finance calculators.
Use these tools to estimate borrowing costs, compare different repayment scenarios, check loan affordability, and plan your repayments based on your own figures. Whether you’re considering a new loan or looking for ways to manage an existing loan more efficiently, these calculators can help you make better-informed financial decisions.
- Personal Loan EMI Calculator – Monthly EMI Calculator
- Car Loan EMI Calculator – Monthly EMI & Interest Calculator
- Home Loan EMI Calculator – Monthly EMI & Interest Calculator
- Education Loan EMI Calculator – Know EMI Before Course Completion
- Free Business Loan EMI Calculator For MSMEs & Startups
- Loan Against Property EMI Calculator – Calculate LAP EMI Online
- Free Term Loan EMI Calculator – EMI, Interest & Amortization
- Free Loan Balance Transfer Calculator: Calculate EMI Savings
- Bike Loan EMI Calculator – Find The EMI That Fits Your Budget
- Gold Loan EMI Calculator – Calculate EMI & Interest Online
- Commercial Vehicle Loan EMI Calculator With EMI Breakdown
- Term Loan Prepayment Calculator – Calculate Interest Savings
- Loan Part Payment Calculator – Save Interest & Reduce EMI
- Home Loan Eligibility Calculator – Check Maximum Loan Eligibility
- Personal Loan Eligibility Calculator – Check Loan Eligibility
- Home Loan Affordability Calculator – Estimate Home Buying Budget
- Loan Tenure Calculator – Calculate Loan Duration From EMI
- Compare Loan Offers Online | Free Loan Comparison Calculator
- Loan Interest Rate Calculator (EMI To Interest Rate) – Free Online
- Loan Amount Calculator – Calculate Maximum Loan Amount From EMI
- Debt-to-Income Ratio Calculator – Check Loan Eligibility
- Rent Vs Buy Calculator Online – Compare EMI, Rent & Investment
- Fixed Vs Floating Interest Rate Calculator – Compare EMI & Interest
- Flat Rate Vs Reducing Rate Calculator – Find Real Interest Rate
- Step-Up EMI Calculator – Calculate Increasing EMI Online
- Loan APR Calculator – Calculate Annual Percentage Rate
- Loan Refinancing Calculator – Calculate EMI & Interest Savings
Subscribe for Finance & Calculator Tips
Disclaimer
The Loan Moratorium Calculator is provided for informational and educational purposes only. Results are indicative estimates based on the outstanding loan balance, interest rate, remaining loan tenure, moratorium period, repayment assumptions, and other information entered by the user. Actual interest accrued, revised EMI, outstanding balance, repayment period, total interest, and overall loan cost may vary depending on the lender, loan agreement, interest calculation method, repayment schedule, capitalization of interest, applicable charges, and other terms.
ToolSuite does not guarantee the accuracy of lender-specific calculations or any particular financial outcome. This calculator should not be considered financial, investment, lending, credit, or professional advice. A loan moratorium may defer scheduled payments without waiving the interest payable during the moratorium period. Always verify the actual moratorium terms, interest treatment, outstanding balance, applicable charges, revised EMI, and repayment schedule with your lender before making any borrowing or repayment decision.