SIP vs Lumpsum: Which Could Grow Your Money More?
Use our Free SIP vs Lumpsum Calculator Online to compare potential returns, total investment, and wealth creation for monthly SIP and one-time lumpsum investments.
SIP vs Lumpsum: Which Investment Approach Is Right for You?
Choosing between SIP and lumpsum investing is not just about how much you invest. It is also about when you invest, how regularly you contribute, and how your money participates in market growth.
SIP Investment
Invest a fixed amount regularly. SIP can help build disciplined investing habits and spread investments over time.
Lumpsum Investment
Invest a larger amount at once. Lumpsum investing puts the money to work immediately, making investment timing more important.
The better choice depends on your investment amount, time horizon, and market conditions. Compare both approaches using the same assumptions before deciding.
Compare Both Strategies
SIP vs Lumpsum Calculator
Compare how a regular monthly SIP and a one-time lumpsum investment could grow over the same investment period. Understand the difference in investment value, returns and final corpus before choosing an investment approach.
Key Takeaway
The calculator compares both investment methods using the same assumed return and investment period.
What Does the SIP vs Lumpsum Calculator Show?
The SIP vs Lumpsum Calculator Online helps you compare the potential outcomes of regular investing and one-time investing using the same investment assumptions.
Estimated maturity value
Compare the potential final value of your SIP and lumpsum investments over the selected investment tenure.
Total investment
See how much you contribute through monthly SIP instalments compared with the amount invested through a one-time lumpsum.
Investment timing
Understand how investing regularly or investing the full amount upfront can lead to different potential outcomes.
Potential wealth creation
Review how the expected return, investment amount, and tenure influence the estimated wealth created under both strategies.
Important: Results are illustrative estimates based on your inputs. Actual investment returns may vary with market performance and investment timing.
What Is SIP vs Lumpsum Investing?
SIP and lumpsum are two common ways to invest in mutual funds and other market-linked investments. The main difference is how and when you invest your money.
Systematic Investment Plan — SIP
A Systematic Investment Plan allows you to invest a fixed amount at regular intervals, usually every month. Each instalment buys investment units at the prevailing market price.
- Investments are spread across different market levels.
- Suitable for regular income and disciplined investing.
- Helps reduce the need to time the market.
Lumpsum Investment
A lumpsum investment involves investing a larger amount in one go. The entire amount is exposed to the market from the investment date and remains invested for the selected period.
- Allows immediate deployment of available capital.
- May benefit when markets rise after investment.
- Returns depend heavily on the entry point and market movement.
Neither strategy guarantees higher returns in every market condition. The better choice depends on your available capital, investment horizon, cash-flow pattern, risk tolerance, and market conditions.
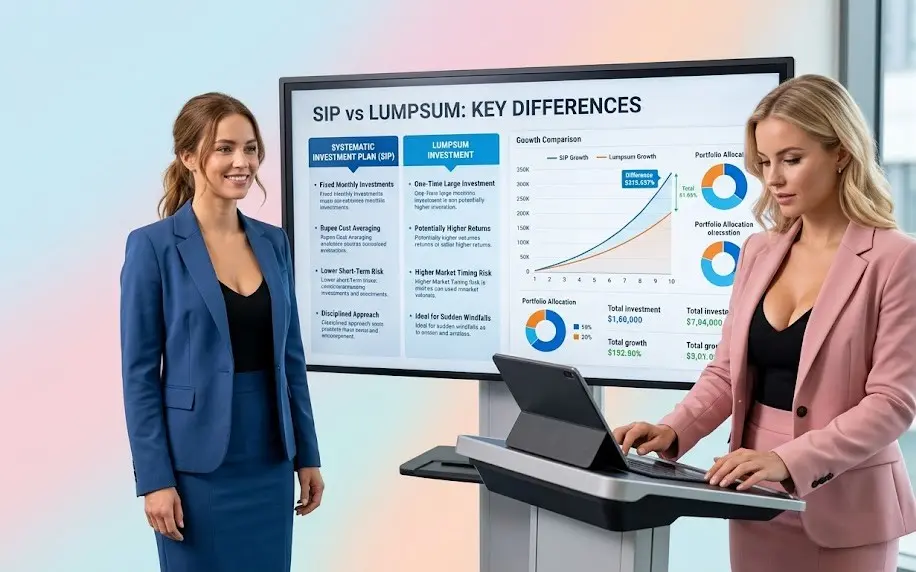
SIP vs Lumpsum: Key Differences
SIP and lumpsum investing differ in investment timing, cash-flow requirements, market exposure, and the way returns may develop over the investment period.
| Comparison Factor | SIP Regular investing | Lumpsum One-time investing |
|---|---|---|
| Investment Method | A fixed amount is invested at regular intervals, usually monthly. | A larger amount is invested in a single transaction. |
| Cash-Flow Requirement | Requires regular surplus income or periodic savings. | Requires a substantial amount of capital at the beginning. |
| Market Exposure | Money enters the market gradually across different dates. | The entire investment is exposed to the market from day one. |
| Market Timing Risk | The impact of investing at an unfavourable market level may be spread across multiple instalments. | The initial market entry point can have a stronger effect on the outcome. |
| Investment Discipline | Encourages consistent saving and long-term investing habits. | Requires the investor to deploy available capital decisively. |
| Return Potential | Returns depend on the timing and performance of each instalment. | Returns depend on the performance of the full amount from the investment date. |
| Suitable For | Investors earning regularly or building wealth through periodic savings. | Investors with existing savings, bonuses, inheritances, or other available capital. |
SIP does not automatically produce higher returns than lumpsum
investing.
The outcome depends on the investment period, market movement,
contribution timing, and the return assumption used in the calculation.
How Does SIP Investment Work?
A Systematic Investment Plan, commonly called a SIP, allows you to invest a fixed amount at regular intervals. Understanding how each instalment is invested helps you interpret the results of a SIP vs Lumpsum Calculator Online.
Choose a Fixed Investment Amount
You select an amount that can be invested regularly, such as ₹2,000, ₹5,000, or ₹10,000 every month. The amount is generally deducted from your bank account on a selected date.
Buy Investment Units at the Applicable NAV
Each SIP instalment purchases units of the selected mutual fund at its prevailing Net Asset Value, or NAV. The number of units purchased changes depending on the market value on that date.
Continue Investing Across Market Levels
When prices are lower, the same instalment may purchase more units. When prices are higher, it may purchase fewer units. This creates the possibility of rupee-cost averaging over time.
Allow Time for Compounding
Over a longer investment horizon, the returns generated by earlier instalments may themselves generate additional returns. This compounding effect can influence the future value of a monthly SIP.
SIP investing can help build discipline and spread investment timing, but it does not guarantee profits or eliminate market risk. Actual SIP returns depend on market performance, investment duration, instalment dates, and the selected investment product.
How Does Lumpsum Investment Work?
A lumpsum investment involves investing a larger amount in one go rather than spreading contributions across multiple instalments. Understanding this approach helps you compare it with SIP through a SIP vs Lumpsum Calculator Online.
What Is a Lumpsum Investment?
In a lumpsum investment, the available capital is invested on a selected date. The entire amount begins participating in market performance from that investment date, allowing the investment to remain exposed to the market for the full selected tenure.
Invest an Available Amount
The investor deploys an existing pool of money, such as savings, a bonus, maturity proceeds, inheritance, or another available source of capital.
Purchase Units at the Applicable NAV
The investment buys units at the mutual fund’s applicable Net Asset Value, or NAV, on the transaction date. The total amount is invested at that point rather than through future instalments.
Remain Invested Through Market Cycles
The full investment experiences market movements from the beginning. The entry level, subsequent market performance, and investment horizon can therefore influence the final value.
Allow Returns to Compound
If the investment generates returns and remains invested, those returns may contribute to future growth. A longer holding period can provide more time for potential compounding.
Lumpsum investing gives the entire capital more time in the market, but it also exposes the full amount to market movements immediately. It may work well when the investor has available capital and a suitable long-term investment horizon.
A lumpsum investment does not guarantee higher returns than SIP. Actual lumpsum returns depend on the investment date, market performance, holding period, asset allocation, and the investment product selected.
SIP vs Lumpsum: Which Is Better?
There is no single investment strategy that is better for every investor. The right choice between SIP and lumpsum depends on your available capital, income pattern, investment horizon, risk tolerance, and prevailing market conditions.
You Prefer Regular Investing
SIP can be suitable when you earn regularly and want to invest a manageable amount every month instead of deploying a large amount at once.
- You receive a regular salary or periodic income.
- You want to build a disciplined investment habit.
- You are investing gradually toward a long-term goal.
- You prefer spreading purchases across different market levels.
- You do not currently have a large amount of investible capital.
You Have Available Capital
Lumpsum investing can be suitable when you already have a substantial amount available and are comfortable investing it for the selected investment period.
- You have savings, a bonus, or another available capital source.
- You want the full amount to participate in the market immediately.
- You have a sufficiently long investment horizon.
- You can tolerate short-term market fluctuations.
- You have a clear asset-allocation and risk-management plan.
If your money becomes available gradually, SIP may be the more practical approach. If you already have a large amount available, lumpsum investing may provide earlier market exposure. You can also consider combining both approaches based on your financial goals and risk profile.
The better choice is not determined only by the projected return. Your liquidity needs, investment discipline, risk capacity, time horizon, and ability to remain invested are equally important when comparing SIP and lumpsum investment.
Factors That Affect SIP and Lumpsum Returns
The projected result of a SIP or lumpsum investment depends on several variables. When using a SIP vs Lumpsum Calculator Online, these factors help explain why the estimated maturity value may change with different inputs.
Expected Rate of Return
The assumed annual return directly influences the estimated future value. A higher assumed return may increase the projected corpus, but actual market returns can be lower or higher.
Investment Tenure
The investment period determines how long the money remains invested. A longer tenure may provide more time for market growth and the compounding of returns.
Investment Timing
SIP instalments enter the market on different dates, while a lumpsum investment is deployed at one point in time. This difference can affect the final investment value.
Market Volatility
Market prices fluctuate over time. Volatility may affect the value of both SIP and lumpsum investments, particularly over shorter investment periods.
Total Investment Amount
In a SIP, the total amount invested depends on the monthly contribution and number of instalments. In a lumpsum investment, the initial capital is invested at the beginning.
Compounding Effect
Returns that remain invested may generate additional returns over time. The effect of compounding becomes more meaningful when the investment remains invested for a longer period.
Calculator projections are not guaranteed outcomes. They are based on the return assumptions, contribution pattern, investment tenure, and other inputs entered by the user. Actual SIP returns and lumpsum returns will depend on future market performance.
How to Use the SIP vs Lumpsum Calculator
Use the SIP vs Lumpsum Calculator Online to compare a monthly SIP with a one-time lumpsum investment. Enter a few basic assumptions to estimate total investment, potential returns, and the projected maturity value under both investment approaches.
Select the Investment Method
Choose whether you want to evaluate a monthly SIP, a one-time lumpsum investment, or compare both methods side by side.
Enter the Investment Amount
Enter the monthly SIP amount for a Systematic Investment Plan or the initial amount for a one-time mutual fund lumpsum investment.
Choose the Investment Tenure
Enter the expected investment duration in years or months. A longer investment horizon can give compounding more time to work.
Enter the Expected Annual Return
Provide an assumed annual return rate for the calculation. This is an illustrative input and does not represent a guaranteed mutual fund return.
Review and Compare the Results
Review the estimated total investment, potential returns, maturity value, and wealth creation shown for the SIP and lumpsum scenarios.
The calculator provides indicative estimates based on the information entered. Actual SIP returns or lumpsum investment returns may differ because of market volatility, changes in NAV, investment timing, expenses, taxation, and the performance of the underlying investment.
Compare SIP vs Lumpsum Now
SIP vs Lumpsum Investment Calculator: Frequently Asked Questions
Find clear answers to common questions about SIP investment, lumpsum investment, return calculations, investment timing, and using the SIP vs Lumpsum Calculator Online.
What is the difference between SIP and lumpsum investment? +
SIP involves investing a fixed amount at regular intervals, usually every month, while lumpsum investment involves investing a larger amount in one transaction. SIP spreads investments across different market levels, whereas lumpsum investment exposes the entire amount to the market from the investment date.
Which is better, SIP or lumpsum investment? +
SIP is generally suitable for regular investing, while lumpsum investment may be more suitable when you have a substantial amount available to invest immediately. SIP can help reduce dependence on a single investment date, whereas lumpsum investment may benefit when the market rises after the initial investment. The better option depends on your cash availability, investment horizon, financial goals, and risk tolerance.
Is SIP safer than lumpsum investment? +
SIP can reduce investment-timing risk because the investment is spread across multiple dates, but it does not eliminate market risk. A lumpsum investment places the entire amount in the market at one time, making the investment more sensitive to market conditions on the investment date. The safety of either method also depends on the underlying mutual fund or investment product.
Does SIP always provide better returns than lumpsum? +
No, SIP does not always provide higher returns than lumpsum investment. If the market rises consistently after the initial investment, lumpsum investment may generate higher returns because the entire amount remains invested for longer. SIP may be more advantageous during volatile or declining markets because contributions are invested at different NAV levels.
How are SIP returns and maturity value calculated? +
SIP maturity value is estimated by considering the periodic investment amount, investment frequency, investment tenure, and assumed rate of return. Each monthly contribution remains invested for a different duration, so the calculation considers the timing of each contribution and the effect of compounding.
How are lumpsum investment returns and maturity value calculated? +
Lumpsum maturity value is estimated by applying the assumed annual return over the selected investment tenure to the initial investment amount. The calculation illustrates how the entire investment may grow through compounding when it is invested at the beginning of the investment period.
What inputs are required in the SIP vs Lumpsum Calculator Online? +
The SIP vs Lumpsum Calculator Online generally requires the monthly SIP amount or initial lumpsum amount, investment tenure, and expected annual return. Depending on the calculator design, users may also enter investment frequency or other assumptions. These inputs are used to estimate total investment, potential returns, and projected maturity value.
Can I use the calculator for mutual fund investments? +
Yes, the calculator can be used to compare the estimated growth of a monthly SIP and a one-time mutual fund lumpsum investment. Enter the relevant investment amount, expected annual return, and investment tenure to compare the projected outcomes.
Should I compare SIP and lumpsum using the same investment amount? +
For a meaningful comparison, use clearly defined assumptions. You may compare the same total investment amount, the same investment tenure, or the same available cash amount, depending on the decision being evaluated. The comparison should make clear whether the difference comes from investment timing, contribution pattern, or total capital invested.
Does the SIP vs Lumpsum Calculator guarantee actual returns? +
No, the SIP vs Lumpsum Calculator does not guarantee actual investment returns. It provides illustrative estimates based on the assumptions entered by the user. Actual returns may vary because of market volatility, changes in NAV, investment timing, expenses, taxation, and the performance of the underlying investment.
SIP and lumpsum calculations are useful for understanding possible outcomes, but they should not be treated as predictions or guarantees. Consider your financial goals, investment horizon, liquidity needs, and risk tolerance before choosing an investment approach.
Recalculate Your SIP vs Lumpsum Comparison
Explore More Investment Calculators
Smart investment planning involves more than deciding how much to invest in a SIP. Explore our free investment calculators to estimate SIP growth, evaluate Step-Up SIP strategies, understand potential returns, and plan for long-term wealth creation.
Use these tools to compare different investment amounts, expected returns, investment tenures, and contribution patterns—whether you’re starting a new SIP, increasing your investment over time, or working towards a specific financial goal.
Related Finance & Investment calculator
- Free Lumpsum Investment Calculator: Maximize The Future Value
- Mutual Fund CAGR Calculator – Calculate Investment Returns
- Free SIP Calculator Online – Calculate Monthly SIP Returns
- SIP Goal Calculator – Monthly SIP Required To Reach Your Goal
- STP Calculator – Plan Mutual Fund Transfers & Estimate Returns
- SWP Calculator – Plan Monthly Withdrawals & Retirement Income
- XIRR Calculator – Find Your True Annual Investment Return (%)
- Step-Up SIP Calculator Online – Calculate SIP Growth & Returns
- Mutual Fund Calculator Online – Calculate Returns & Growth
- Investment Goal Calculator Online – Plan Your Future Corpus
- Free Inflation Calculator: Estimate Future Cost Of Living
- Home Loan Eligibility Calculator – Check Maximum Loan Eligibility
- Personal Loan Eligibility Calculator – Check Loan Eligibility
- Home Loan Affordability Calculator – Estimate Home Buying Budget
- Debt-to-Income Ratio Calculator – Check Loan Eligibility
- Rent Vs Buy Calculator Online – Compare EMI, Rent & Investment
- Fixed Vs Floating Interest Rate Calculator – Compare EMI & Interest
- Flat Rate Vs Reducing Rate Calculator – Find Real Interest Rate
- Step-Up EMI Calculator – Calculate Increasing EMI Online
- Loan APR Calculator – Calculate Annual Percentage Rate
- Loan Refinancing Calculator – Calculate EMI & Interest Savings
Get Smarter Investment Insights in Your Inbox
Disclaimer
The SIP vs Lumpsum Calculator is provided for informational and educational purposes only. The results are indicative estimates based on the investment amount, investment frequency, expected annual return, investment tenure, and other information entered by the user. Actual investment value, returns, maturity value, total investment, and wealth creation may vary depending on market conditions, investment timing, changes in NAV, fund performance, expenses, taxation, and other factors.
The calculator does not guarantee any returns and should not be considered investment, financial, or tax advice. The assumed rate of return is used only for illustration and may not reflect the actual performance of any mutual fund or investment product. Users should evaluate their financial goals, investment horizon, liquidity requirements, and risk tolerance before making investment decisions.